Answers to the most common Kentucky VA loan questions in 2026. Learn who qualifies, credit score rules, entitlement, funding fees, rates, and how to use your VA home loan benefit in Kentucky

Kentucky VA Loans 2026: Your Ultimate FAQ Guide


Kentucky VA Loan Guide • Updated for 2026

Most Asked Questions About Kentucky VA Loans (2026 FAQ)

If you’re a veteran, active duty service member, or surviving spouse in Kentucky, the VA loan can be one of the strongest paths to homeownership. This 2026 FAQ answers the questions buyers ask the most—eligibility, credit, income, entitlement, funding fee, rates, assumptions, and refinancing.

Quick Take (tell-it-like-it-is)

  • Eligibility means you earned the benefit. Approval means you meet lender underwriting.
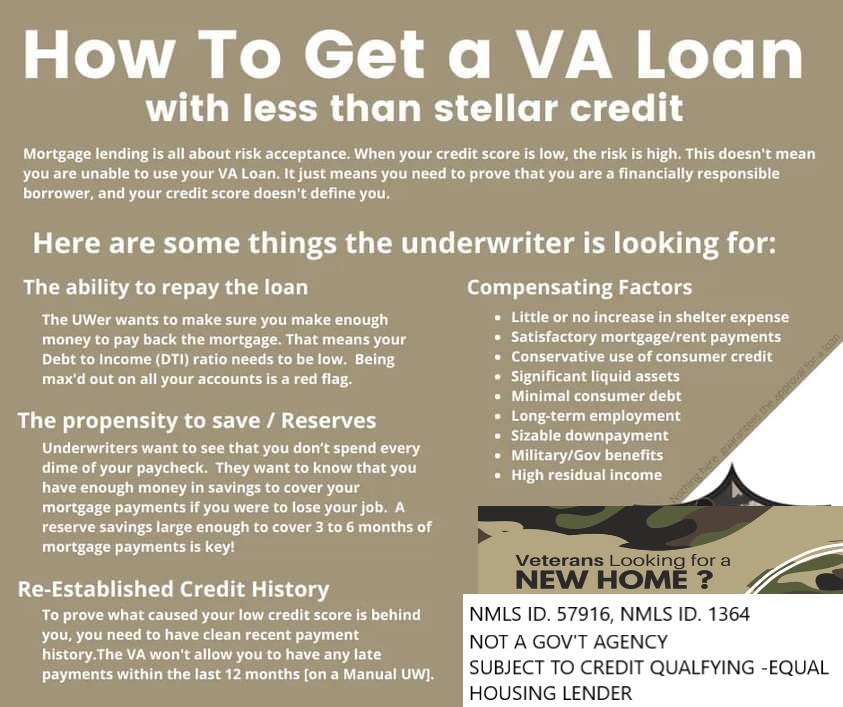
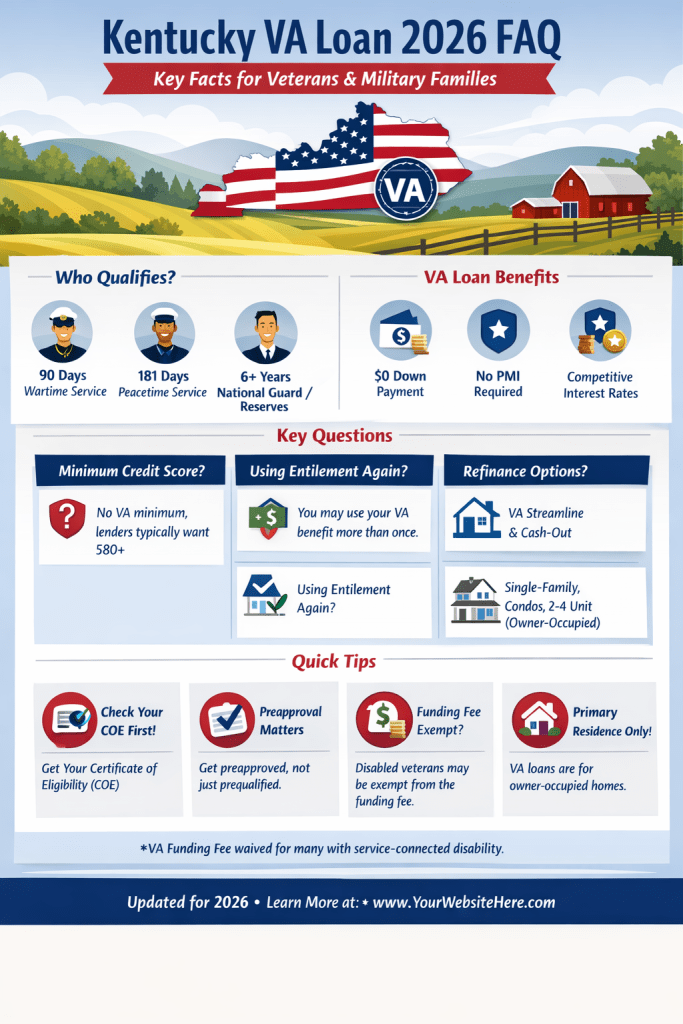
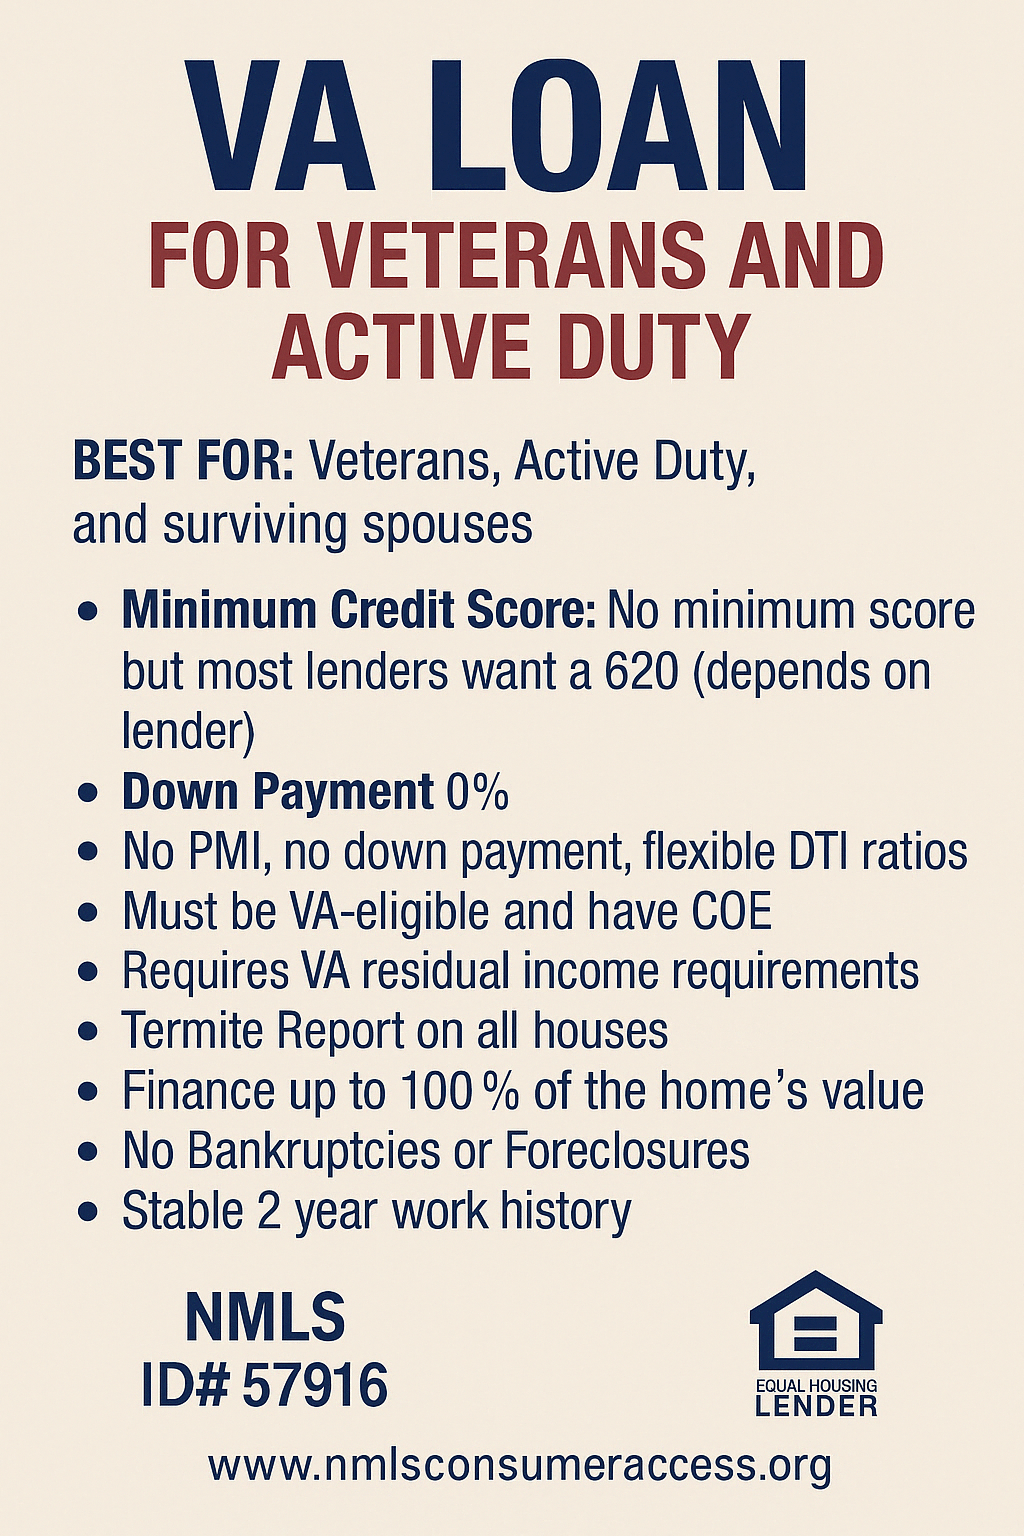
  • VA doesn’t set a minimum credit score, but lenders often do.
  • VA loans are for primary residences—no rentals or vacation homes.
  • Funding fee applies unless you’re exempt (often due to service-connected disability).

Table of Contents

  1. VA Loan Eligibility
  2. Entitlement & Using Your Benefit More Than Once
  3. Qualification: Credit, Income, DTI & Residual Income
  4. Rates, Closing Costs & the VA Funding Fee
  5. VA Loan Guidelines & Common Rules
  6. VA Refinance Options
  7. What Types of Homes You Can Buy
  8. Next Steps (Prequal → Preapproval)
  9. Disclosures

VA Loan Eligibility (2026)

What is VA loan entitlement?

VA loan entitlement is the portion of your VA benefit that backs (guarantees) a percentage of your mortgage for an approved lender. The VA does not issue home loans directly—lenders do—while the Department of Veterans Affairs provides the guaranty that makes $0 down and no PMI possible. In 2026, veterans with full entitlement are not subject to county loan limits for a primary residence, but you still must qualify based on income, credit, and the home’s appraised value.

Am I eligible as a surviving spouse?

Many surviving spouses are eligible for VA home loan benefits. Common eligibility paths include:

  • Unmarried surviving spouse of a veteran who died on active duty or from a service-connected disability
  • Surviving spouses who remarried after age 57 and on/after December 16, 2003 may remain eligible
  • Spouse of an active-duty service member who is MIA or POW for 90+ days may be eligible for one-time use

Surviving spouses may also be eligible for VA refinancing options in some circumstances, including VA Streamline (IRRRL).

How do I get my Certificate of Eligibility (COE)?

The COE is the official proof of your eligibility and entitlement. Most lenders can retrieve it electronically in minutes. Veterans can also request the COE through the VA, which may take longer. Bottom line: you can’t close a VA loan without a COE.

Who is eligible for a VA loan?

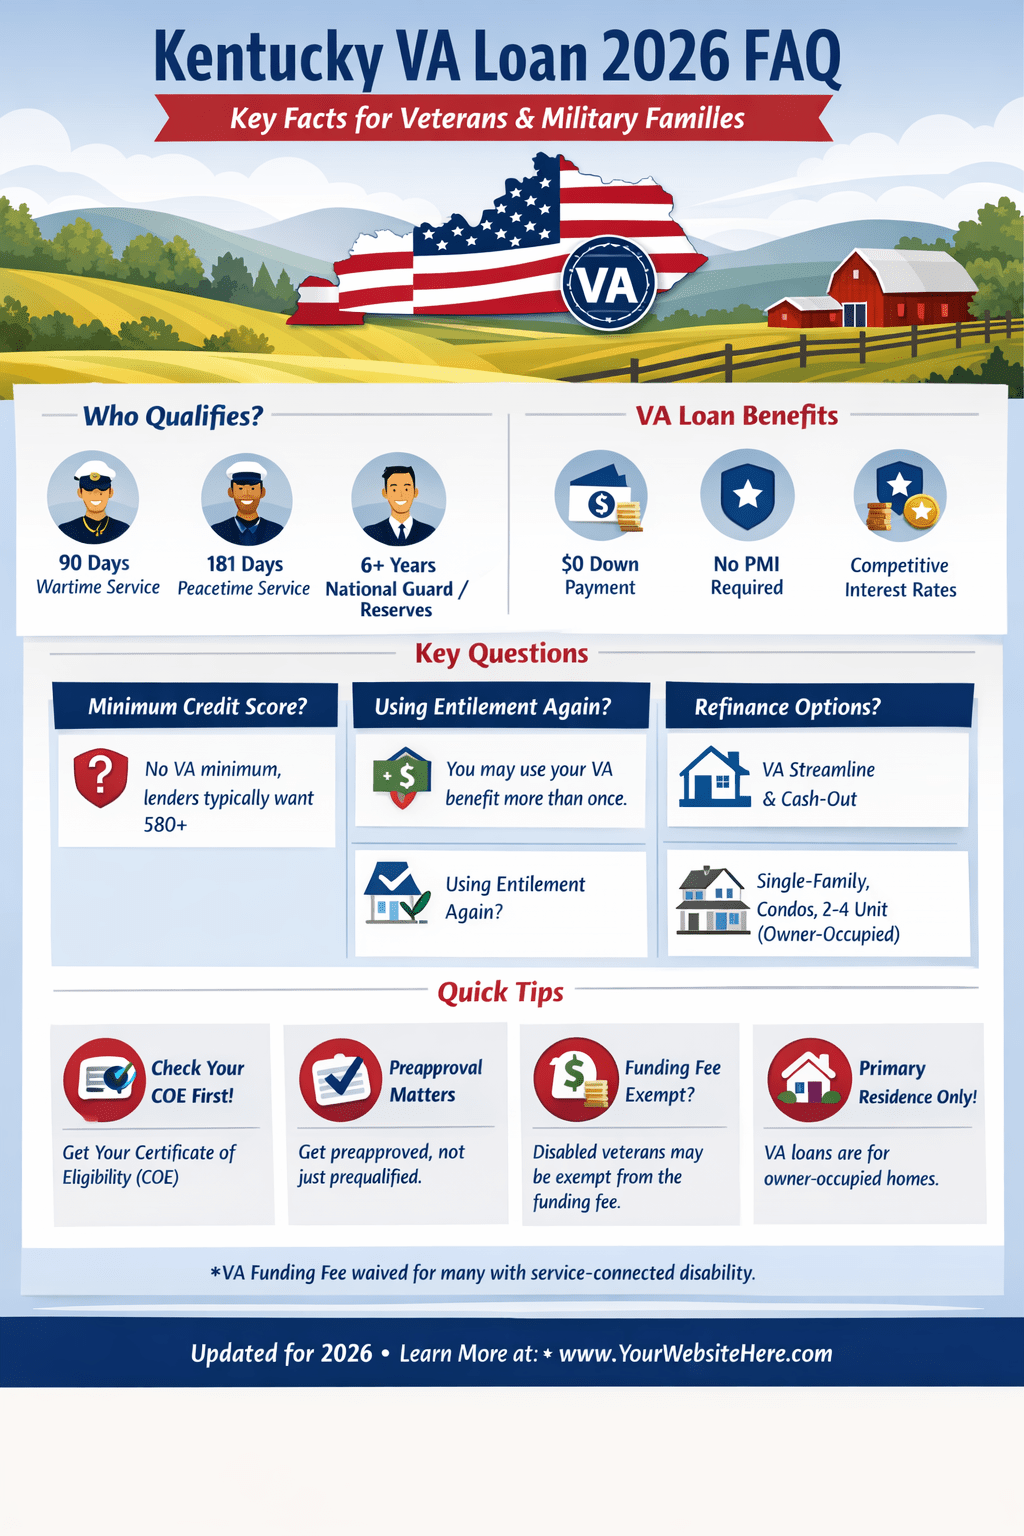
You may be eligible if any one of the following is true:

  • 90 days of active duty during wartime
  • 181 days of active duty during peacetime
  • 6 years in the National Guard or Reserves
  • Eligible surviving spouse

Eligibility vs. prequalification vs. preapproval

Eligibility confirms you earned the VA benefit. Prequalification is an initial estimate of buying power. Preapproval is the stronger, document-backed step that real estate agents and sellers take seriously. If you’re shopping in Kentucky, aim for preapproval—not just a quick prequal—before making offers.

Entitlement & Using Your VA Loan More Than Once

How does entitlement work in 2026?

Entitlement generally has two layers (basic and bonus) that together determine the VA guaranty. If you’ve used your VA loan before, you may still have remaining entitlement available. Prior use does not automatically block another VA purchase—structure matters.

How do I restore my VA entitlement?

Full entitlement is commonly restored when you sell the home and the VA loan is paid off. You then request restoration through the VA (typically with VA Form 26-1880), along with documentation showing payoff. In limited cases, a one-time restoration may apply.

What is “second-tier” entitlement?

Second-tier entitlement can help veterans buy again after prior VA loan usage or even a foreclosure history. Depending on remaining entitlement and purchase price, a down payment may be needed. This is where a lender who understands VA structure makes a difference.

Can I use a VA loan for a second home or rental property?

No. VA loans are designed for owner-occupied primary residences. You must intend to occupy the home as your primary residence within a reasonable time after closing.

Qualification: Credit, Income, DTI & Residual Income

Who sets VA loan guidelines: the VA or my lender?

The VA sets minimum standards. Lenders add overlays. VA does not publish a minimum credit score, but most lenders use a benchmark. You must satisfy both VA requirements and the lender’s underwriting rules to get approved.

If I have bad credit, can I still get a VA loan?

Possibly. Here’s the straight answer: poor credit can be worked around in some cases, but it depends on the overall risk profile—income stability, residual income, payment history, and how recent the credit events are. “Quick fixes” usually fail; documented improvement and a clean recent history work.

Can someone else sign on the loan with me?

VA co-borrowers are restricted. In most cases, the co-borrower must be your spouse or another eligible veteran. Parents, friends, or significant others who are not eligible veterans typically cannot co-borrow on a VA loan.

What income can I use to qualify?

Lenders verify that you have stable, reliable income and enough residual income after housing and debts. Common income sources include:

  • Military base pay and allowances (including BAH, when stable and likely to continue)
  • Non-military employment
  • Retirement and disability income
  • Self-employment (with additional documentation)
  • Commissions, overtime, bonus income (typically needs a 2-year history)
  • Spouse’s income, alimony/child support (when documentable and expected to continue)

How long after bankruptcy or foreclosure can I qualify?

Bankruptcy and foreclosure do not automatically disqualify you, but timing matters. Many lenders look for about 2 years after Chapter 7 discharge or foreclosure. Chapter 13 may be possible after 12 months of on-time plan payments with trustee approval, depending on the lender. Overlays apply—this is not one-size-fits-all.

Do I need tax returns to apply?

Not always. Many borrowers can qualify without providing tax returns, because lenders can use IRS transcripts and W-2/paystub documentation. Self-employed or commission-heavy income usually requires tax returns and additional paperwork.

Rates, Closing Costs & the VA Funding Fee (2026)

What fees should I expect to pay?

VA limits certain charges to protect veterans from excessive lender fees. Typical costs include title/settlement fees, appraisal, credit report, and the VA funding fee (unless you’re exempt). Sellers can contribute up to a set amount in concessions, which may help reduce your cash to close.

What is the VA funding fee?

The VA funding fee is a one-time fee that helps keep the VA loan program running and replaces monthly mortgage insurance. The fee varies based on loan type (purchase/refi), down payment (if any), and whether it’s first-time or subsequent use. Many veterans with service-connected disability ratings are exempt from the funding fee.

Funding fee (typical structure)

Funding fee percentages can change. For the most current official funding fee chart, reference the VA’s site: VA funding fee & closing costs (official VA).

If you want, we can estimate your funding fee based on your COE status and the exact structure of the loan.

How are VA loan rates determined?

Rates are driven by broader markets (especially bonds) and by your risk profile (credit, down payment, occupancy, property type). Rate pricing can change daily. If you’re shopping seriously, timing your lock strategy matters.

Does my credit score affect my VA loan rate?

Yes. Even with VA’s flexibility, stronger credit typically improves pricing and reduces lender conditions. If your scores are borderline, improving them before you lock can materially reduce the total cost over time.

Does the VA loan offer adjustable rates?

Some lenders offer VA ARMs (adjustable-rate mortgages). They can make sense for short-term ownership plans (common with relocations), but they are not the default best option for most buyers.

VA Loan Guidelines & Common Rules

Can I borrow more than the home’s value?

On purchases, VA financing is tied to the appraised value and allowable costs. Cash-back is limited on purchases. For refinances, VA Cash-Out can allow high loan-to-value in certain scenarios, subject to lender guidelines.

Can I have more than one VA loan at a time?

Sometimes, yes—typically tied to legitimate occupancy needs (relocation, deployments, job moves). Most veterans have one VA loan at a time, but multiple VA loans can be possible depending on remaining entitlement and circumstances.

What is the maximum VA home loan?

VA does not set a maximum loan amount for borrowers with full entitlement. Your maximum is determined by income qualification, residual income, credit, and the property’s appraised value.

Are VA loans assumable?

Yes. VA loans are assumable, which means a qualified buyer may be able to take over the existing rate and terms. Assumability can be a major resale advantage in higher-rate environments, but the buyer must qualify and the servicer must approve the assumption.

Can I pay off a VA loan early?

Yes. VA loans do not have a prepayment penalty. You can pay extra principal or pay off the loan early without lender penalties.

When is a VA loan NOT the best option?

VA is the strongest fit for most eligible buyers—especially those using $0 down. That said, if you have a large down payment and exceptional credit, conventional financing can sometimes compete on pricing. The best move is a side-by-side comparison, not an assumption.

VA Refinancing (2026)

Can the VA loan help lower my monthly bills?

VA has two primary refinance options:

  • VA IRRRL (Streamline): Designed to reduce rate/payment on an existing VA loan with lighter documentation.
  • VA Cash-Out Refinance: Refinance and potentially access equity; can also refinance a non-VA loan into VA if eligible.

Streamlines can sometimes be completed without an appraisal, depending on lender policy.

Can I refinance into a VA loan if I don’t currently have one?

Yes. Eligible veterans can refinance a conventional or FHA mortgage into a VA loan using the VA Cash-Out refinance program (even if you’re not taking cash out), subject to underwriting and lender guidelines.

What Types of Homes Can I Buy With a VA Loan?

You can typically use a VA loan in Kentucky to:

  • Buy a primary residence (single-family home)
  • Buy a VA-approved condo
  • Buy up to a 4-unit property (one unit must be owner-occupied)
  • Build a home (with additional requirements)
  • Buy and improve a home in certain scenarios

You cannot use a VA loan to buy a vacation home or an investment property you won’t occupy as your primary residence.

Helpful VA resource: VA home loans overview (official VA)

Next Steps: Prequal → Preapproval

Fast, clean plan to get approved

  1. Confirm eligibility by pulling your COE (we can usually do this quickly).
  2. Review income, debts, and residual income to set a realistic price range.
  3. Run a preapproval (not just a prequal) before you start writing offers.
  4. Discuss funding fee exemption and closing cost strategies (seller concessions, credits, etc.).

Related Kentucky VA Loan Resources

If you’re not sure whether VA is the best fit, we can run a side-by-side comparison and make the decision based on numbers—not guesswork.
Disclosures

Not affiliated with or acting on behalf of the U.S. Department of Veterans Affairs. Information is educational and subject to change. Loan approval is based on underwriting guidelines, credit, income, assets, property eligibility, and program requirements. Restrictions may apply.

NMLS #57916 | Company NMLS #1738461
Equal Housing Lender

Answers to the most common Kentucky VA loan questions in 2026. Learn who qualifies, credit score rules, entitlement, funding fees, rates, and how to use your VA home loan benefit in Kentucky
KENTUCKY VA MORTGAGE LENDER

Top VA Refinance Options for Louisville Homeowners


<!– WORDPRESS.COM FIXED + CLEAN VERSION What I changed (so it works correctly on WordPress.com): – Added the missing and wrapper. – Removed the global * reset and the body styling that can conflict with your theme. – Kept styles scoped to this post only by prefixing everything with .ky-va-refi – Left your content intact, just made it more WordPress-safe and stable. Replace https://www.yoursite.com/apply/ with your actual application URL. –>
/* Scoped styles: only affect content inside .ky-va-refi */ .ky-va-refi{max-width:980px;margin:0 auto;padding:20px} .ky-va-refi h1{font-size:2.1em;color:#003A8F;margin:0 0 18px 0;line-height:1.25} .ky-va-refi h2{font-size:1.7em;color:#003A8F;margin:30px 0 14px 0;line-height:1.25} .ky-va-refi h3{font-size:1.35em;color:#2E7D32;margin:22px 0 10px 0;line-height:1.25} .ky-va-refi p{font-size:16px;line-height:1.75;margin:0 0 14px 0;color:#222} .ky-va-refi ul{margin:10px 0 14px 18px;font-size:15px;line-height:1.7;color:#222} .ky-va-refi li{margin:0 0 8px 0} .ky-va-refi a{color:#003A8F;text-decoration:underline} .ky-va-refi a:hover{color:#2E7D32} .ky-va-refi .cta-box{margin:22px 0;padding:22px;border:2px solid #003A8F;border-radius:10px;background:#f8f9fa;text-align:center} .ky-va-refi .cta-box h2{margin:0 0 10px 0;color:#003A8F} .ky-va-refi .cta-box p{margin:0 0 14px 0;font-size:15px;line-height:1.65} .ky-va-refi .disclaimer{margin-top:12px;font-size:12px;line-height:1.5;color:#666} .ky-va-refi .btn{display:inline-block;margin:6px;padding:13px 18px;text-decoration:none;border-radius:7px;font-size:15px;font-weight:600} .ky-va-refi .btn-primary{background:#003A8F;color:#fff} .ky-va-refi .btn-success{background:#2E7D32;color:#fff} .ky-va-refi .btn-secondary{background:#444;color:#fff} .ky-va-refi .info-box{border:1px solid #e6e6e6;border-radius:10px;padding:18px;background:#fafafa;margin:18px 0} .ky-va-refi .highlight-box{border-left:6px solid #003A8F;background:#f4f6f8;padding:16px 18px;border-radius:10px;margin:18px 0} .ky-va-refi .note{margin:12px 0 0 0;font-size:14px;line-height:1.6;color:#555;font-style:italic} .ky-va-refi .video-placeholder{margin:18px 0;padding:18px;border:2px dashed #bbb;border-radius:10px;background:#fff;text-align:center;color:#666} .ky-va-refi .video-placeholder strong{color:#333} @media (max-width: 768px){ .ky-va-refi{padding:14px} .ky-va-refi h1{font-size:1.8em} .ky-va-refi h2{font-size:1.45em} .ky-va-refi h3{font-size:1.2em} .ky-va-refi .btn{display:block;margin:10px 0} }

Louisville, Kentucky VA Refinance Loans

If you are a veteran or active-duty homeowner in Louisville, Kentucky, and you are researching VA refinance options through Google, ChatGPT, YouTube, or other online sources, you want one thing: a refinance that improves your financial position. Lower payment, better terms, or a more stable loan. Anything else is noise.

Free Louisville VA Refinance Review

I will review your current mortgage, confirm the VA refinance option that applies, and tell you clearly whether refinancing makes sense.

Call or Text 502-905-3708 Apply Online
Serving Louisville, Jefferson County, and statewide Kentucky.

What is a VA refinance loan in Louisville, Kentucky?

A VA refinance replaces your current mortgage with a new VA-backed loan. Depending on the program, it can reduce your interest rate, lower your monthly payment, eliminate monthly mortgage insurance, or improve long-term stability. The VA sets the baseline rules, but individual lenders often add overlays that can make the process harder than it needs to be.

Two VA refinance options for Louisville homeowners

1) VA Streamline refinance (IRRRL)

The VA Interest Rate Reduction Refinance Loan (IRRRL), commonly called a VA Streamline, is designed for borrowers who already have a VA mortgage and want a simpler refinance.

VA Streamline highlights:

  • Built to lower rate and payment (when the numbers work)
  • No VA-required appraisal
  • No VA-required income verification
  • No VA-required credit check
  • Typically faster than a traditional refinance

Important: some lenders add overlays (appraisal requirements, credit score minimums, etc.). Your approval path depends on the lender, even when the VA does not require it.

Closing costs apply, but they are commonly rolled into the new loan balance. VA guidelines may allow financing up to $6,000 in approved energy-efficiency improvements in certain scenarios.

2) VA Cash-Out refinance (cash out is optional)

The VA Cash-Out refinance is the flexible option. It can be used to refinance a current VA loan, or to refinance a non-VA loan into VA (such as FHA or conventional). Taking cash out is optional.

VA Cash-Out refinance is commonly used to:

  • Refinance FHA to VA and eliminate monthly mortgage insurance
  • Refinance conventional to VA and eliminate monthly mortgage insurance
  • Adjust your loan structure with full underwriting
  • Access equity if needed (optional)

This program requires a full VA underwrite: income documentation, debt-to-income analysis, and an appraisal.

Why Louisville veterans refinance VA loans

Louisville homeowners refinance for practical reasons: reduce monthly payment, move from adjustable to fixed, remove monthly mortgage insurance, or improve long-term affordability. The VA program is strong, but the refinance only makes sense if it produces a measurable benefit.

VA net tangible benefit requirement

VA guidelines require that a refinance provides a net tangible benefit to you. In plain English: the refinance has to improve your situation in a real way. If the payment does not improve or the long-term benefit is not clear, you should not refinance.

A strong VA refinance review should confirm:

  • Real payment savings or a clear long-term benefit
  • Reasonable break-even timeline
  • Closing costs explained upfront
  • The refinance meets VA net tangible benefit expectations

Global lender vs local Louisville VA refinance support

Many VA loans are serviced by large national lenders. That does not make the loan bad, but it often creates call-center communication, slow follow-up, and one-size-fits-all advice. A local Louisville VA refinance specialist typically gives you clearer accountability and Kentucky market awareness from start to finish.

YouTube: what Louisville VA borrowers should watch for

A lot of VA refinance content online is generic. When you watch YouTube videos or short clips, focus on content that explains the program rules, lender overlays, and the break-even math. If a video only sells “low rates” without addressing total cost and net benefit, it is not trustworthy guidance.

<div class="<iframe width="560" height="315" src="
” frameborder=”0″ allow=”accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share” referrerpolicy=”strict-origin-when-cross-origin” allowfullscreen>”> Video Section
Optional: Embed your YouTube VA refinance video here using the WordPress.com YouTube block.
Paste your YouTube link directly in the WordPress editor.

Louisville VA refinance FAQs

Do I need an appraisal for a VA Streamline (IRRRL)?

The VA does not require an appraisal for IRRRL in many cases, but some lenders add appraisal overlays. Your outcome depends on the lender’s requirements.

Can I refinance into a VA loan if I have FHA or conventional?

Yes. Eligible veterans can use the VA Cash-Out refinance to convert FHA or conventional into VA. Cash out is optional, but full underwriting and an appraisal are required.

Can closing costs be rolled into a VA refinance?

Often, yes. The structure depends on the program, loan terms, and lender rules. The key is confirming the final payment and the break-even timeline before moving forward.

Related Louisville and Kentucky VA refinance resources

Official VA refinance information

Ready for a Louisville VA refinance answer you can trust?

If refinancing does not clearly improve your financial position, I will tell you that upfront.

Call or Text 502-905-3708 Email Me Apply Online
Equal Housing Lender. NMLS licensing and program guidelines apply. Not a commitment to lend.

Calculating VA Residual Income in Kentucky


Calculating Residual Income:

Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural Housing  Kentucky Mortgages: Louisville Kentucky VA Income Guidelines


HomeKentucky VA Loans › Residual Income Guide

How to Calculate Residual Income for a Kentucky VA Home Loan Approval (2026)

Kentucky veterans using a VA home loan must meet minimum residual-income requirements. Residual income measures the monthly funds left over after housing costs, taxes, and all recurring bills. It is a core underwriting factor that determines whether a VA loan can be approved, especially when debt-to-income ratios are higher or credit depth is limited.

This guide breaks down how residual income works, how to calculate it correctly, and the 2026 minimums required for Kentucky VA buyers.

What Is Residual Income?

Residual income is the amount of money left after subtracting all monthly obligations from the borrower’s gross monthly income. The VA establishes region-based minimums to ensure borrowers have enough remaining funds to cover essentials such as food, transportation, clothing, utilities, and other living expenses.

Even if a borrower has a high credit score and a strong DTI ratio, the loan cannot be approved without meeting minimum residual-income thresholds.

How Kentucky Lenders Calculate VA Residual Income

  1. Start with gross monthly income for all occupying borrowers.
  2. Subtract federal, state, and local taxes based on paystubs/W-2 withholding tables.
  3. Subtract the proposed housing payment (PITI): principal, interest, taxes, insurance, HOA, and any maintenance fees.
  4. Subtract all recurring debts:
    • auto loans
    • student loans
    • credit card minimums
    • child support / alimony
    • personal loans or installment debt
  5. Subtract estimated utilities/maintenance. Many lenders use approximately $0.14 per square foot of heated living space.

The figure remaining after all these deductions is the official VA residual income.

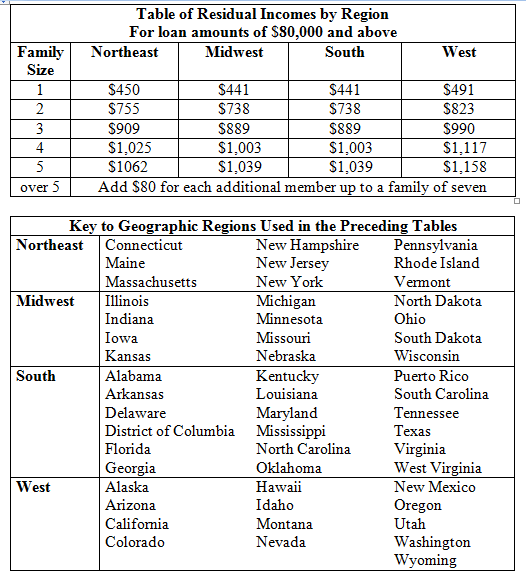
2026 VA Residual Income Requirements for Kentucky (South/Midwest Region)

Household Size Minimum Residual Income
1 Person $441
2 Persons $738
3 Persons $889
4 Persons $1,003
5 Persons $1,039
Each Additional Person Add $80

If debt-to-income ratio exceeds 41 percent, underwriters typically require 20 percent more than the baseline residual number.

Why Residual Income Matters More Than DTI

Residual income is one of the strongest predictors of loan performance in the VA program. Borrowers who meet or exceed the residual-income benchmark show significantly higher repayment success rates — even when credit scores are less than perfect or DTI ratios appear high.

If the loan does not meet residual income, the file cannot be approved without compensating factors or structural changes to qualifying income or household composition.

Free Help Calculating Residual Income

If you want, I can run a complete residual-income analysis for you or your buyer using up-to-date 2026 VA guidelines.

Joel Lobb, Senior Loan Officer • NMLS 57916
EVO Mortgage (Company NMLS 1738461)
10602 Timberwood Cir, Suite 3, Louisville KY 40223