Kentucky USDA Mortgage Lender for Rural Housing Loans


Kentucky USDA loans, backed by the U.S. Department of Agriculture, are designed to help low to moderate-income borrowers in Kentucky rural areas achieve homeownership

If you’re considering buying a home in Kentucky and looking for a mortgage loan with favorable terms, a Kentucky USDA loan could be a great option. Kentucky USDA loans, backed by the U.S. Department of Agriculture, are designed to help low to moderate-income borrowers in Kentucky rural areas achieve homeownership. Here’s a comprehensive guide on how to get approved for a USDA mortgage loan in Kentucky in regards to credit score, income, work history, debt to income ratios, bankruptcy and foreclosure :

  1. Kentucky USDA loans Credit Score Requirements:
    • While Kentucky USDA loans are known for their lenient credit score requirements compared to conventional loans, having a good credit score can still improve your chances of approval. Aim for a credit score of 640 or higher for smoother processing. On paper USDA says there is no minimum score, but it is very difficult to get approved with lenders with no score.
  2. Kentucky USDA loans Income Eligibility:
    • USDA loans have income eligibility criteria based on the area’s median income. To qualify, your household income should fall within the USDA’s income limits for the specific county or area in Kentucky where you plan to buy a home.
  3. Kentucky USDA loans Work History:
    • Lenders typically look for a stable work history, preferably with at least two years of consistent employment in the same field or industry. This demonstrates your ability to repay the loan.
  4. Kentucky USDA loans Property Location (Counties 120 in Kentucky):
    • USDA loans are specifically designed for properties located in eligible rural areas or designated suburban areas. Before applying, ensure that the property you’re interested in is within a USDA-eligible location in Kentucky.
  5. Kentucky USDA loans Income Ratio:
    • Your debt-to-income (DTI) ratio is an important factor in loan approval. Generally, USDA loans require a DTI ratio of 41% or lower, although some lenders may allow higher ratios with compensating factors.
  6. Kentucky USDA loans Income Limits:
    • USDA loans have income limits based on family size and county location. These limits vary by area, so check the current income limits set by USDA for the county where you plan to purchase your home.
  7. Kentucky USDA loans Property Type:
    • USDA loans are intended for primary residences, including single-family homes, townhouses, and eligible condominiums. Investment properties and vacation homes are not eligible.
  8. Kentucky USDA loans Bankruptcy and Foreclosure Requirements:
    • Having a bankruptcy or foreclosure in your financial history doesn’t necessarily disqualify you from a USDA loan. However, there are waiting periods after these events before you can apply:
      • Chapter 7 bankruptcy: 3 years from the discharge date.
      • Chapter 13 bankruptcy: 1 year of on-time payments and court approval.
      • Foreclosure: 3 years from the sale date.
  9. Kentucky USDA loans Closing Time:
    • USDA loans typically take around 30 to 45 days to close, although this timeline can vary based on factors such as application volume and the efficiency of document processing.
  10. Kentucky USDA loans Appraisal Requirements:
    • A professional appraisal is required for USDA loans to determine the fair market value of the property. The appraisal ensures that the property meets USDA standards and is worth the loan amount.
  11. Kentucky USDA loans Termite Inspections:
    • USDA loans may require a termite inspection, especially in areas where termite infestations are common. The inspection aims to identify and address any termite-related issues in the property.
  12. Kentucky USDA loans GUS (Guaranteed Underwriting System):
    • GUS is a tool used by lenders to process USDA loan applications. It evaluates the borrower’s credit, income, and other factors to determine eligibility and streamline the underwriting process.
  13. Kentucky USDA loans Manual Underwriting:
    • In some cases, USDA loans may undergo manual underwriting, especially if the borrower’s application doesn’t meet automated approval criteria. Manual underwriting involves a more thorough review of the borrower’s financial situation by the lender.

Kentucky USDA loan

To get a Kentucky USDA loan, potential Kentucky rural housing borrowers must follow this sequence of steps:

  1. Determine eligibility by consulting online USDA maps.
  2. Decide whether you want a guaranteed or direct loan. Guaranteed loans will have higher income limits, which you’ll work out with the lending institution.
  3. Submit all applicable paperwork, including income, debts, and credit reports.
  4. After pre-approval, begin searching for new homes (or launch renovations on your current home).

Keep in mind that you’ll have fees associated with your loan. Guaranteed loans require an upfront 1% fee and annual fees of 0.35% for as long as the mortgage is active.

USDA program for properties located outside urban areas of Kentucky areas where you can secure a no money down loan at a  fixed rate of on 30 years.

The max household income limits usually are between  $110,500 to $146,000 for most rural area counties depending on household family size.

 This changes every year so make sure you are using updated USDA Income Limits for this year 

A 620-640 middle credit score is needed for loan approval on this program. They’re no max loan limits on USDA loans. You just need to qualify based on your debt to income ratio (see below under income section)—–USDA will go down to 580 on scores but it has to pass  USDA Manual Underwriting guidelines

Need to be 3 years removed from a Chapter 7 Bankruptcy and 3 years from a foreclosure

Joel Lobb  Mortgage Loan Officer

American Mortgage Solutions, Inc.
10602 Timberwood Circle
Louisville, KY 40223

Text/call: 502-905-3708
fax: 502-327-9119
email:
 kentuckyloan@gmail.com
http://www.mylouisvillekentuckymortgage.com/
Kentucky USDA loans, backed by the U.S. Department of Agriculture, are designed to help low to moderate-income borrowers in Kentucky rural areas achieve homeownership
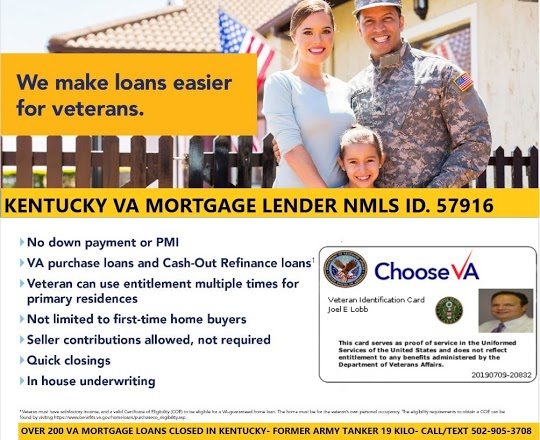
Kentucky VA Mortgage Loan Guide for Home Buyers 2 Votes VA Mortgage Loan Guide for Kentucky Veterans and Active Duty Soldiers and Reservists You may be looking to purchase a home in Kentucky. This is true if you’re a veteran, active-duty service member, or eligible surviving spouse. VA mortgage loans offer one of the best financing options available. VA loans have no down payment requirements. They also offer competitive interest rates and no private mortgage insurance (PMI). These loans are designed to make homeownership more accessible for those who have served our country. Below, we’ll explore everything you need to know about Kentucky VA loans, including common myths, eligibility requirements, and benefits. What Is a Kentucky VA Loan? A VA loan is a mortgage program backed by the U.S. Department of Veterans Affairs (VA) to help veterans and active-duty military members buy or refinance a home. The VA does not issue the loans directly. Instead, it guarantees a portion of them. This reduces the risk for lenders and enables better loan terms for borrowers. Benefits of Kentucky VA Loans No Down Payment: Unlike conventional loans, VA loans allow 100% financing, meaning no down payment is required (in most cases). No PMI (Private Mortgage Insurance): VA loans save you hundreds of dollars monthly by eliminating the need for PMI. Competitive Interest Rates: VA loans often have lower interest rates compared to conventional loans. Flexible Credit Requirements: VA loans have more lenient credit score requirements. They also have more favorable debt-to-income (DTI) ratio requirements. This makes them accessible to borrowers with less-than-perfect credit. Assumable Loans: VA loans can be transferred to qualified buyers, a valuable feature when interest rates rise. Reduced Costs for Disabled Veterans: Veterans with service-related disabilities may have the VA funding fee waived. Common Myths About Kentucky VA Loans Myth #1: VA Loans Are Hard to Qualify For Fact: VA loans are actually easier to qualify for compared to conventional loans. They have more lenient credit requirements, allowing for lower credit scores and higher DTI ratios. Most lenders prefer a credit score of 620 or higher. However, some may approve borrowers with scores as low as 580. Myth #2: VA Loans Require a Down Payment Fact: VA loans offer 100% financing, meaning no down payment is required for homes under the local conforming loan limit. For homes above this limit (jumbo loans), a down payment may be necessary based on your remaining VA loan entitlement. Myth #3: VA Loans Require PMI Fact: VA loans do not require PMI, even when financing 100% of the home’s value. This saves borrowers thousands over the life of the loan. However, there is a VA funding fee, which can be financed into the loan or waived for eligible veterans. Myth #4: You Can Only Use a VA Loan Once Fact: There is no limit on how many times you can use your VA loan benefit. You can use the VA loan program multiple times throughout your life. Just make sure you meet eligibility requirements and entitlement limits. Myth #5: VA Loans Are Not Assumable Fact: VA loans are assumable, meaning another buyer can take over your mortgage. This is particularly advantageous if interest rates rise. Buyers must meet VA loan eligibility requirements and qualify based on income and credit. Eligibility Requirements for a Kentucky VA Loan To qualify for a VA loan, you must meet the following requirements: Military Service: 90 consecutive days of active duty during wartime, OR 181 days of active duty during peacetime, OR 6 years in the National Guard or Reserves. Credit Score: While the VA has no minimum credit score, lenders typically require a 620+ score. Some lenders accept scores as low as 580. Residual Income: You must meet residual income requirements to ensure you can afford the loan. Property Eligibility: The property must meet VA standards, including safety, sanitation, and structural soundness. Occupancy: You must use the home as your primary residence. How to Get a VA Loan in Kentucky Obtain Your Certificate of Eligibility (COE): This document proves you are eligible for a VA loan. You can obtain it through the VA’s eBenefits portal, your lender, or by submitting VA Form 26-1880. Choose a VA-Approved Lender: Work with a lender experienced in VA loans, like Joel Lobb, Mortgage Loan Officer, who specializes in Kentucky VA loans. Pre-Qualify for a Loan: Provide basic financial and service information to determine your eligibility and loan amount. Find Your Home: Work with a realtor familiar with VA loan requirements to find a home that meets VA property standards. Close the Loan: After approval, your lender will coordinate the closing process, and you’ll get the keys to your new home. VA Loan Refinancing Options in Kentucky VA IRRRL (Streamline Refinance): Lower your interest rate with minimal paperwork and no appraisal or credit check. VA Cash-Out Refinance: Use your home equity to access cash for home improvements, debt consolidation, or other needs. Why Work With Joel Lobb for Your Kentucky VA Loan?

Comparing Kentucky VA loans to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky


Kentucky VA loans Compared to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky

When comparing Kentucky VA loans to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky, several factors come into play, including credit score requirements, income considerations, work history, debt ratios, and how each loan type treats bankruptcy and foreclosure. Let’s delve into the benefits and differences of each loan type:

Kentucky Mortgage Credit Score Requirements:

  • Kentucky VA Loan: VA loans typically have more flexible credit score requirements compared to conventional loans. While there’s no specific minimum score set by VA , most Kentucky VA lenders often look for a credit score of 620 or higher. I can do VA loans down to a 580 credit score.
  • Kentucky USDA Loan: USDA loans also offer flexibility, with no minimum score required per USDA guidelines, but most Kentucky USDA lenders will want a 640 score or higher. I Can do Kentucky USDA loans down to a 580 credit score on a manual underwrite.
  • Kentucky FHA Loan: FHA loans are known for accommodating borrowers with lower credit scores, often accepting scores as low as 500 with a 10% down payment or 580 with a 3.5% down payment.
  • Kentucky Fannie Mae Loan: Fannie Mae loans usually require a minimum credit score of 620 or higher, although some lenders may have slightly different requirements.

Kentucky Mortgage Income and Work History:

  • Kentucky VA Loan: VA loans consider your stable income and employment history but may be more lenient if you have a history of military service or steady employment. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky USDA Loan: USDA loans often have income limits based on the area’s median income, and you need a stable income source. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky FHA Loan: FHA loans consider your income stability and work history, with guidelines that vary by lender. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky Fannie Mae Loan: Fannie Mae loans typically require a stable income and employment history, similar to conventional loans. 2 years of employment needed for loan application-minimal job gaps

Kentucky Mortgage Debt Ratio Requirements:

  • Kentucky VA Loan: VA loans generally have more lenient debt-to-income (DTI) ratio requirements, often allowing for a higher DTI compared to conventional loans. VA loans can get approved on much higher debt to income ratios vs FHA, USDA and Fannie Mae loans. 65% or higher in some situations but if manual underwrite, will want the ratios closer to 41% with good residual income for VA loan. VA loans are the only type of loans that require a residual income…FHA, Fannie Mae, USDA does not have residual income requirements
  • Kentucky USDA Loan: USDA loans have very strict DTI ratio limits, typically around 41% to 45% max on the backend ratio and 33% or less on the front end. By far the most restrictive on debt ratios vs FHA, VA, and Fannie Mae loans
  • Kentucky FHA Loan: FHA loans also have relatively flexible DTI ratio limits (56% back end ratio possible on a AUS approval), making them accessible to borrowers with moderate levels of debt. Front end ratio max 45%
  • Fannie Mae Loan: Fannie Mae loans follow standard DTI ratio guidelines similar to conventional loans. TYpically the second most restrictive on debt ratios right behind USDA loans on tighter debt to income ratio requirements, with the max back-end ratio no more than 50% –Front end ratio max 45%

Kentucky Mortgage Bankruptcy and Foreclosure Requirements:

  • Kentucky VA Loan: VA loans are more forgiving of past bankruptcy or foreclosure, often requiring a waiting period of 2 years for Chapter 7 bankruptcy and 1-2 years for foreclosure.
  • Kentucky USDA Loan: USDA loans have specific waiting periods after bankruptcy (3 years for Chapter 7) and foreclosure (3 years).
  • Kentucky FHA Loan: FHA loans have shorter waiting periods after bankruptcy (2 years for Chapter 7) and foreclosure (3 years).
  • Kentucky Fannie Mae Loan: Fannie Mae loans typically require longer waiting periods after bankruptcy (4-7 years) and foreclosure (7 years).

Advantages and Disadvantages of Kentucky VA loans, USDA, Fannie Mae and FHA:

  • Kentucky VA Loan Advantages: Zero down payment, competitive interest rates, no private mortgage insurance (PMI) requirement, lenient credit and DTI ratios, and flexible eligibility criteria for veterans and active-duty service members.
  • Kentucky VA Loan Disadvantages: Funding fee (although it can be rolled into the loan), limited to eligible veterans, service members, and some spouses.
  • Kentucky USDA Loan Advantages: Zero down payment, lower interest rates, flexible credit requirements, and available in eligible rural areas.
  • Kentucky USDA Loan Disadvantages: Limited to rural properties, income limits, and property eligibility criteria.
  • Kentucky FHA Loan Advantages: Low down payment (3.5%), flexible credit requirements, competitive interest rates, and accessible to first-time homebuyers.
  • Kentucky FHA Loan Disadvantages: Mortgage insurance premiums (MIP), stricter property standards, and limits on loan amounts.
  • Kentucky Fannie Mae Loan Advantages: Available for a wide range of properties, competitive interest rates, and options for low down payments.
  • Kentucky Fannie Mae Loan Disadvantages: Stricter credit and DTI requirements, potential for private mortgage insurance (PMI), and limited flexibility for borrowers with past financial challenges.

In summary, choosing the right loan type depends on your specific financial situation, eligibility criteria, and property location. VA loans offer excellent benefits for eligible veterans and service members, while USDA, FHA, and Fannie Mae loans provide alternatives with their own advantages and considerations.

Joel Lobb  Mortgage Loan Officer

American Mortgage Solutions, Inc.
10602 Timberwood Circle
Louisville, KY 40223
Company NMLS ID #1364

Text/call: 502-905-3708
fax: 502-327-9119
email:
 kentuckyloan@gmail.com
http://www.mylouisvillekentuckymortgage.com/
NMLS 57916  | Company NMLS #1364/MB73346135166/MBR1574

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
NMLS ID# 57916, (www.nmlsconsumeraccess.org).