Kentucky VA Mortgage with Seller Concessions for Closing Costs and Paying Off Debts Guideline


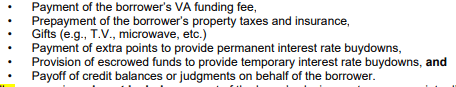
The max seller paid closings costs on a Kentucky VA loans is 4% and with the concessions that can include payoffs of credit balances: 

👇
VA Mortgage Seller Concessions Rule

The Department of Veterans Affairs defines a Seller Concession as “…anything of value added to the transaction by the builder or seller for which the buyer pays nothing additional and which the seller is not customarily expected or required to pay or provide.“

The seller’s paying of the buyer’s closing costs is not considered a Seller Concession.  A Seller Concession is considered anything paid to the buyer outside of the normal closing costs that is offered to make the sale more attractive to a buyer.  These concessions often come in the form of the seller paying such pre-paid items as the Homeowners Insurance premium or the amount needed for property tax escrows.

Another common concession is the seller agreeing to pay the VA Funding Fee on behalf of the veteran or paying the lender discount points to buy down the interest rate on the Veteran’s new VA mortgage.  VA Funding Fees are typically financed by the Veteran, so when the seller agrees to pay this cost, this fee does not need to be financed, resulting in lower loan amount and lower payment for the Veteran.  By paying discount points to buy down the Veteran’s interest rate, the result can be savings in the thousands over the life of the loan.

These Seller Concessions can even include such items as appliances, TVs, furniture, lawn mowers, etc.   If such items are used they need to be listed with a reasonable value assigned to each.

One of the more interesting Seller Concessions allows for the seller to payoff a borrower’s liability, such as a collection, a judgement or a credit balance.  Sometimes there is a particular account on a credit report that is preventing a potential home buyer from qualifying for a mortgage.  Paying off this account can be offered as a Seller Concession and make the difference between the buyer qualifying and not qualifying for a VA mortgage.

Seller Concessions often include the following…

  • paying the pre-paid items such as insurance premiums and tax escrows
  • paying the VA Funding Fee
  • offering such gifts as TVs, appliances, furniture and other houshold items which are not typically included
  • paying off a borrower liabilty such as a collection, judgement or credit balance

Is there a limit to the amount of Concessions a Seller can offer?

The Department of Veteran Affairs has capped the amount of Seller Concessions to 4% of the sales price. 

Why is their a 4% cap on Seller’s Concessions?

The intent with the cap is to offer protection to the Veteran against overly aggressive Seller Concessions which may tempt Veterans into attempting the purchase a home that may really stretch their budget beyond true affordability.

Wait a minute… you mentioned some items like appliances, TV and furniture can be offered as Seller Concessions, how do we know how much these are worth to make sure their value is within this 4% cap?

For sellers to properly offer such concessions they must provide the buyer and lender with an itemized list of the concessions to be offered.  The list needs to make sense and be reasonable.  Claiming a 46″ LCD TV is worth $5000 would certainly raise an eyebrow.  The list is subject to approval by the VA so make sure these types of concessions are reasonable and fall within the 4% cap.

So just to confirm……If a seller pays any of the buyer’s closing costs it is not considered a Seller’s Concession?

That is correct.  The seller can pay all of the buyer’s closing costs without limit and these closing costs are not included in the Sellers Concession 4% cap. If there are closing costs that are considered excessive or are not typical for the area, they can be then included in as a Seller Concession.   Since the VA also allows the seller to pay these costs without limit, the result is that the Veteran can often come to the closing table with no money needed.

Thank you,

Kentucky VA Home Loans for 2021


Kentucky VA Home Loans for 2021


.

  •  No down payment in most cases for purchase loans (up-front money toward your home purchase), and easier borrower credit requirements.
  •  No monthly mortgage insurance premiums or private mortgage insurance (PMI).
  •  Lower homebuyer closing costs, and limits to what borrowers can be charged.
  •  The opportunity to roll your “VA funding fee” into your mortgage.
  • The ability to refinance a non-VA loan into the VA mortgage program.
  •  The opportunity to: ask a home seller to contribute up to 4 percent of the mortgage amount to cover some of the closing costs; ask your lender to cover some of the closing costs; seek closing cost assistance through state homebuying programs created for veterans and first-time buyers.
  • The right to become a VA borrower for life. In most cases you can use VA mortgage programs forever, and sometimes you can have more than one VA loan.
  •  Eligibility of financing for spouses of service-members who died in the line of duty or from a service-related disability.

You can review all types of Kentucky VA Home Loans here, including purchase mortgages, refinance mortgages (called Interest Rate Reduction Refinance Loans or IRRRLs), and cash-out refinance loans.

To qualify for a Kentucky VA Home Loan, usually a military veteran or service-member must have 90 consecutive days of active service during wartime, or 181 straight days of service during peacetime, or six years in the national guard or reserves of a particular military branch. You can find out if you’re eligible here.

Kentucky  VA mortgage comes with an additional closing cost called a “VA funding fee” of between 1.4 to 3.6 percent on the amount borrowed (depending on your circumstance). This special fee that non-VA borrowers never have to pay helps partially fund the “government backed” part of the VA borrower program, and many VA borrowers can roll it into their mortgage.

VA Loan Quick Facts

0% Down
Minimum Down Payment
620 Credit
Minimum Credit Score
41% DTI
Max Debt-to-Income Ratio


What is a VA Loan?

VA Loans are designed to assist veterans purchase a home. Active duty military and veterans across the nation will enjoy the desirable loan terms and low interest rates that often come with a VA loan. Additional benefits like no down payment requirement help make home buying an affordable and cost-effective reality for those who have served and continue to serve our country.

What are the benefits of a VA Loan?

VA Loan benefits and features:

  • Zero down payment
  • Buyers may finance the funding fee into the loan
  • Closing costs may be covered
  • Buyers may use gifts and seller contributions to cover closing costs

Who may benefit from a VA Loan?

A VA Loan may the right fit for you if:

  • You’re an eligible veteran or active-duty military
  • You’re buying a first home or are a repeat homebuyer

hgjhgjhgjjhgjhj

KENTUCKY VA HOME LOANS


KENTUCKY VA HOME LOANS

Kentucky VA loans require little to no money down. Also, you will not pay a monthly mortgage insurance premium (MIP) or an upfront fee like you would with a conventional, low-down-payment home loan.

The VA does not have a private mortgage insurance (PMI) requirement.

Kentucky VA Loan Eligibility Requirements

Only certain veterans and their spouses qualify for VA-backed mortgages. The good news is the qualifications are not as strict as you think. Here are the VA’s eligibility requirements:

• Active-duty service for 181 days during peacetime
• Active-duty service for 90 consecutive days during wartime
• Member of the Reserves or National Guard for six consecutive years
• Married to a veteran who died as a result of a service-connected disability or in the line of duty

Remember that it is ultimately up to the lender to decide to give you a loan. You will still need to meet certain requirements outlined by the bank or mortgage company.

Basic and Bonus Entitlement

The VA refers to your eligibility to borrow money using a VA-backed mortgage as your basic and bonus entitlement. The word “entitlement” is another word for insurance. However, your basic and bonus entitlement are not the same, but you can use them at the same time. Here is how they work:

When you receive your certificate of eligibility (COE) from the VA, it will show you are eligible for $36,000 in basic entitlement. Fortunately, the $36,000 on your COE is not the maximum amount you can borrow. The figure is how much the VA will pay if you default on your loan.

Most banks and mortgage lenders will lend you up to four times your basic entitlement, which is $144,000 ($36,000 x 4 = $144,000). So, using your basic entitlement, you can borrow up to $144,000 to buy a home. You might be thinking $144,000 is not enough to buy a home in most places, and you are right. This is where your bonus entitlement kicks in.

Kentucky VA Home Loan Refinance Information

You can use your VA home loan entitlement for more than just buying a house. You can use it to reduce the interest rate on an existing loan (known as an IRRRL), or you can take out some equity in your home with a 90% to 100 percent cash-out refinance.

Additionally, you can use a VA home loan more than once as long as you have not used all of your basic and bonus entitlement. Now that you know the facts behind VA mortgages, you should comfortably find the loan program that fits your needs.